Categories
Recent Posts
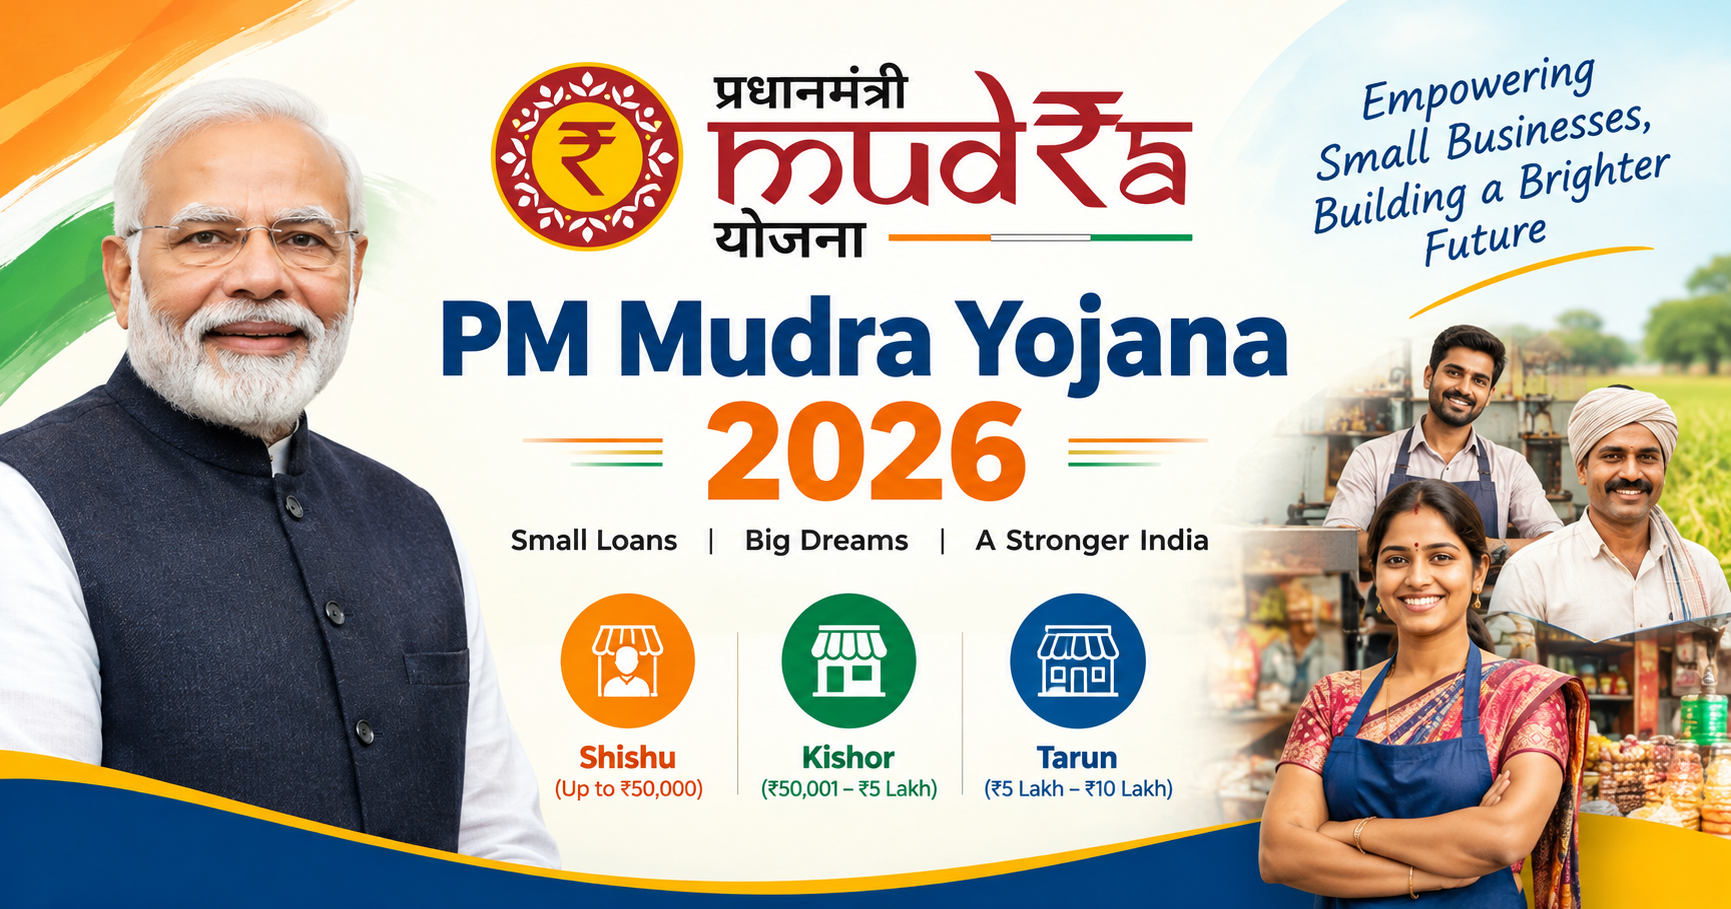
Table of Contents
PM Mudra Yojana 2026: Get Up to ₹20 Lakh Business Loan Without Collateral
Last Updated: September 2026 ·
Running a small business without enough money to grow is one of the quiet fears most Indian entrepreneurs carry. You have the idea, the skill, maybe even your first few customers — but banks ask for collateral you don't have, and private lenders charge interest that eats your profit before you even start.
The Pradhan Mantri MUDRA Yojana (PMMY) exists to remove exactly that fear. It lets you borrow up to ₹20 lakh for your business without pledging your house, shop, or gold — just your plan and your will to work.
If you're a founder, shopkeeper, or self-employed professional stuck on "no collateral, no loan," this guide covers everything in plain English: how much you can get, who qualifies, what papers you need, and exactly how to apply, step by step.
What Is PM Mudra Yojana (PMMY)?
Pradhan Mantri MUDRA Yojana (PMMY), launched in April 2015 by the Government of India, is a credit scheme that provides collateral-free loans up to ₹20 lakh to small and micro, non-farm enterprises.
The scheme is run through MUDRA (Micro Units Development & Refinance Agency Ltd.), which does not lend directly to individuals. Instead, MUDRA refinances banks, NBFCs, NBFC-MFIs, and Regional Rural Banks — and they lend to you under PMMY.
In short: you apply at your bank or a listed lender, never at MUDRA itself — and no one should ever ask you to pay an "agent fee" to get a Mudra loan, because MUDRA uses no agents or middlemen.
Loan Amount / Financial Assistance Under PMMY
|
Category |
Loan Amount |
Best Suited For |
Tenure |
|---|---|---|---|
|
Shishu |
Up to ₹50,000 |
Brand-new / very early-stage businesses |
Up to 5 years |
|
Kishor |
₹50,001 – ₹5 lakh |
Established businesses needing funds to grow |
Up to 7 years |
|
Tarun |
₹5 lakh – ₹10 lakh |
Mature micro-enterprises planning expansion |
1–7 years |
|
Tarun Plus |
₹10 lakh – ₹20 lakh |
Entrepreneurs who already took and fully repaid a Tarun loan |
Up to 7 years |
Note: Tarun Plus is only for repeat borrowers with a clean MUDRA repayment history — first-time applicants cannot apply directly for it.
Interest rates are not fixed by the government. Each bank or NBFC sets its own rate based on your credit profile and loan category (broadly 8%–18%+ depending on the lender). Women entrepreneurs may get a small concession (around 0.25%) at some banks. Always confirm the exact rate with your chosen lender before signing.
Eligibility Criteria
- Indian citizen, aged 18 to 65
- Running or planning a non-farm, income-generating small/micro business — manufacturing, trading, services, or allied agri-activities (poultry, dairy, beekeeping, fisheries, etc.)
- Can apply as an individual, sole proprietor, partnership firm, or small private company/MSME
- Should not be a loan defaulter with any bank or financial institution
- No fixed minimum income required — a workable business idea or existing small business matters more than your salary slip
- For Tarun Plus specifically: must have taken a Tarun loan earlier and repaid it with a clean record
Benefits Of A Mudra Loan
- 100% collateral-free — no property, gold, or guarantor needed
- No processing fee on Shishu loans at most banks
- Backed by the Credit Guarantee Fund for Micro Units (CGFMU), which lowers lender risk and makes approval easier for you
- Comes with a RuPay Mudra Debit Card for flexible working-capital withdrawals at ATMs/POS machines
- Flexible repayment tenure — up to 7 years depending on category
- Priority consideration for women, SC/ST, and OBC entrepreneurs
- Funds can be used for working capital, machinery, raw material, or expansion — not locked to one single purpose
Documents Required
Identity & address proof: Aadhaar card, PAN card, Voter ID, passport (if available); a utility bill not older than 2 months
Business proof: Udyam Registration Certificate / GST Certificate / Trade License (wherever applicable); proof of business address
Financial documents: Last 6 months' bank statements; for Tarun and Tarun Plus — Income Tax Returns (ITR) and balance sheet/profit-loss statement for 1–2 years; a simple project report or business plan (mandatory for Kishor, Tarun, and Tarun Plus)
Other: 2 recent passport-size photographs; SC/ST/OBC certificate (if claiming category benefit); quotation for machinery/equipment to be purchased (if applicable)
How To Apply — Step By Step
Online (recommended):
- Visit the official Jansamarth portal or Udyamimitra portal.
- Select Business Loans → Mudra Loan from the scheme list.
- Check your eligibility using the built-in calculator.
- Register with your mobile number and verify via OTP.
- Fill in your personal, business, and financial details, and pick your loan category (Shishu / Kishor / Tarun / Tarun Plus).
- Upload the required documents.
- Compare in-principle offers from different lenders on interest rate and tenure.
- Accept an offer, complete the lender's final verification, and receive disbursal directly into your bank account.
Offline:
- Visit the nearest branch of a public sector bank, private bank, regional rural bank, small finance bank, or NBFC-MFI offering Mudra loans.
- Collect the PMMY loan application form (also downloadable from the bank's website).
- Fill the form and attach the required documents.
- Submit at the branch and track status using your application/reference number.
Official Website Links
- Jansamarth Portal — Government of India's national portal for credit-linked schemes
- Udyamimitra Portal — SIDBI-backed platform dedicated to Mudra loan applications
- Official MUDRA website — for scheme information (MUDRA does not lend directly or use agents)
Important: MUDRA never charges a fee to process your loan and never operates through agents or middlemen. If anyone asks for money in MUDRA's name, it is almost certainly a scam — apply only through your bank or the official portals above.
Who Should Apply
- First-time entrepreneurs starting a small shop, trading unit, or service business with little to no collateral
- Existing business owners who need working capital or equipment funds to grow (Kishor/Tarun)
- Women entrepreneurs, and SC/ST/OBC founders, who get priority and sometimes rate concessions
- Self-employed professionals — tailors, beauticians, small manufacturers, food-stall owners, artisans, repair-shop owners
- Past Tarun borrowers with a clean repayment history, now eligible for the larger Tarun Plus loan up to ₹20 lakh
- Not suitable for: large corporates, pure farming income (direct agriculture is better covered under schemes like Kisan Credit Card), or applicants already in default with another lender
Common Mistakes To Avoid
- Submitting Aadhaar/PAN details that don't exactly match the name and address on other documents — causes rejection or delay
- Applying without a clear, written business plan for loans above ₹50,000 — a vague plan is the most common reason for rejection
- Having frequent cheque bounces or an irregular current account history before applying
- Approaching unauthorized "Mudra agents" who promise guaranteed approval for a fee — MUDRA uses no agents
- Applying for the wrong category (e.g. asking for Tarun Plus as a first-time borrower, which isn't allowed)
- Not comparing interest rates across lenders — since the government doesn't fix the rate, shopping around genuinely saves money
- Skipping GST/Udyam registration where applicable, which delays disbursal